Upstream cost inflation drives October polymer prices higher.
High crude oil and energy costs are finally feeding through into October polymer prices. In many cases, producers will seek increases above the rise in feedstock costs to recover some margin.
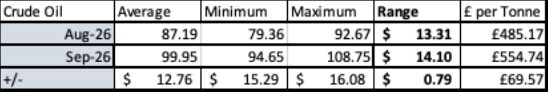
Although demand remains muted, the supply-demand balance has shifted in sellers’ favour compared with recent months, with tangible evidence of tightness in some material types and grades. Feedstock prices remain elevated relative to the start of the year, although the surge associated with the US-Iran conflict in April and May has subsided against a backdrop of persistently high crude oil prices.
The outlook remains uncertain. Seasonal demand associated with Christmas appears to be arriving later than in previous years, which may affect the extent of year-end discounting. If supply chains become depleted, producers may have less need to push inventory through the market as converter demand wanes, particularly if polymer production continues at normal levels. Buyers should therefore remain alert to grade-specific availability and avoid assuming that softer year-end demand will automatically translate into lower prices.
Monomer Price Movement
Feedstock
Price per Tonne
Change (contract)
C2 (Ethylene)
£1,331.12
£68.49
C3 (Propylene)
£1,275.56
£68.49
SM (Styrene Monomer)
£1,695.04
£238.85
Benzene
£1,023.02
£223.44
Butadiene
£1,014.46
£214.88
Brent Crude (monthly average)
£554.74
£68.69
Exchange Rates
€
1.17
$
1.35
€/$
1.16
Mike Boswell Executive Chairman – Plastribution Group
In October, European polyolefin producers are seeking price increases following higher ethylene and propylene contract settlements, driven by the rise in naphtha and broader feedstock costs. The size of the increase varies by grade: tighter LDPE availability provides the strongest support, and most producers are targeting an increase above the monomer settlement of €80 / MT. Adequate supply and continued subdued demand are likely to limit just a monomer pass-through on LLDPE, HDPE and PP.
Geopolitical risk and feedstock volatility remain important; oil pricing has been consistently $100+ per barrel this month. Imported material remains sensitive to shipping costs, exchange rates and trading offers reflect this.
The short-term outlook is firm but mixed. Producers are targeting increases to recover higher raw-material costs, but converters remain cautious and demand is not strong enough across most grades to support increases beyond monomer.
LDPE remains the firmest polyethylene grade in October. Restricted European availability, order controls and ongoing production issues are supporting further increases, with suppliers seeking to pass through higher ethylene costs and recover margin. Buyers should expect increases to be more successful here than in other commodity PE grades, although the outcome will still depend on grade and supplier position.
LLDPE
Supply
Demand
LLDPE suppliers are seeking increases in October in response to higher ethylene and replacement costs. Imported offers from the US and Middle East provide some competition, but freight, exchange-rate and supply-chain risks are keeping delivered costs firm. Demand remains cautious and attempts at increases above monomer have been swiftly rejected
HDPE
Supply
Demand
HDPE prices are under upward pressure in October as producers attempt to reflect the higher ethylene contract and naphtha costs. Supply is generally adequate and demand remains muted so producers hoping for some margin recovery are being more realistic in offers later in the month. Blow moulding, film and injection grades are settling differently according to local availability and stock position. Blow moulding grades appear to be the most in demand.
PP
Supply
Demand
PP producers have announced increases for October following the rise in the propylene contract and higher naphtha costs. Initial attempts to achieve beyond the monomer have been abandoned as ample availability and weak downstream demand continue to give buyers a strong position. The market is expected to firm selectively, with outcomes varying by grade, supplier and customer commitment.
PS
Supply
Demand
PS pricing is moving sharply higher in October after a substantial rise in the European styrene reference contract, supported by stronger benzene and feedstock costs. Producers are seeking sizeable increases for both GPPS and HIPS. Weak underlying demand may restrict margin expansion, but the scale of the styrene movement means a significant cost-led increase is necessary.
Other Polyolefins
EVA is firmer in October as higher ethylene costs support producer increases, although improved availability and cautious demand may limit the scale of movement. POP and POE remain comparatively resilient, with speciality grades continuing to track monomer costs, import replacement values and individual supply positions more closely than commodity polyolefins.
The market is generally still eerily quiet with unusually low levels of activity. Rollover is expected on most material types for October as supply and ample stocks will cover the subdued demand.
The Benzene contract price for October settled at €1195/t, up by €261/t from September, mainly due to the volatility in the oil price. Whether this filters through to relevant polymer prices remains to be seen, but the suspicion is probably not because of the poor demand and high stocks.
Pete Tillin Product Manager – Performance Polymers
Performance Polymer Feedstocks £/Metric Tonne by month
No Data Found
ABS
Supply
Demand
Due to low demand and abundant supply, ABS prices are still under some downward price pressure, however the composite raw material costs have gone up massively, so ABS costs are also under a lot of upwards pressure. Who knows which way they will ultimately go?
For reference, the styrene monomer contract price increased by €279/t for October, it now stands at €1980/t. In addition, butadiene went up by €50/t and ACN by €91/t.
PA6
Supply
Demand
High stock levels and ample availability, coupled with low demand means that prices will more than likely remain around current levels, despite calls for cost increases, which some producers have actually already implemented for quarter four.
PA66
Supply
Demand
The situation for PA66 is broadly the same as PA6, so despite rumours of price increases, and in some cases actual price hikes, the market remains very subdued so there could even be some reductions.
POM
Supply
Demand
As with many other performance polymers, demand is still subdued and there are no real drivers for any major changes in market prices. The longer-term view is that prices may reduce towards the end of the year
PC
Supply
Demand
The market for PC remains quiet and abundant supply means that prices may reduce over the next few months, despite upward price pressure on some key raw materials.
PMMA
Supply
Demand
Due to the low demand and high stock levels/good availability, prices will likely rollover or even reduce slightly.
PBT
Supply
Demand
A comparable situation to most other engineering materials.
Other Engineering Polymers
The situation for most other engineering materials is similar, with market prices under downward pressure, demand generally low and availability good.
Recycled polyolefin prices have been broadly stable in October to date, with only limited firming for higher-quality natural and translucent grades. Rising virgin polymer costs have improved the backdrop for recyclates, but weak underlying demand, competitive imports and cautious converter purchasing continue to restrict the pass-through of increases. The broader European recycling sector therefore remains under significant margin and operating-cost pressure.
Recycled LDPE / LLDPE prices have remained broadly at rollover in October to date. Higher-quality natural and translucent grades are the most resilient where recycled content is specified, while black and grey grades remain under greater competitive pressure. Firmer virgin polyethylene costs have reduced some of the downward pressure, but adequate availability, imports and cautious buying continue to limit any meaningful upward movement.
Recycled HDPE
Supply
Demand
Recycled HDPE prices have also been largely stable in October to date. Natural grades continue to receive the strongest support from packaging, consumer goods and sustainability-led applications, while mixed-colour and industrial grades remain more readily available. Higher virgin HDPE replacement values have strengthened seller sentiment, although subdued demand means increases are difficult to secure unless material quality, colour and certification requirements are clearly met.
Recycled PP
Supply
Demand
Recycled PP prices remain close to rollover in October to date. Natural and light-coloured grades continue to attract the strongest interest where higher-quality recycled content is required, while darker industrial grades remain well supplied. Firmer virgin PP costs offer some support, but weak end-user demand and continued competition from lower-priced virgin and imported material are preventing recyclers from achieving broad-based increases.
Contact Mike Boswell
Executive Chairman
Contact Ian Chisnall
Product Manager – Sustainable Polymers
Contact Pete Tillin
Product Manager – Performance Polymers
The latest updates sent straight to your inbox
Simply enter your details below to subscribe to Price Know-How